Here’s the article on long-term mutual funds for 2026 wealth creation.
Key Takeaways
- Focus on equity-oriented mutual funds, particularly those with a strong track record in large-cap and flexi-cap categories for robust long-term growth.
- Consider Balanced Advantage Funds (BAFs) for a blend of equity and debt, offering stability and potentially beating inflation in volatile markets.
- Diversification across sectors and fund types is crucial; don’t put all your eggs in one basket.
- Look for funds with consistent performance, experienced fund managers, and reasonable expense ratios for optimal returns.
Navigating the Investment Landscape for 2026 Wealth Creation
As we look towards 2026, the Indian economy is poised for continued growth, presenting a fertile ground for long-term wealth creation through mutual funds. Many of you are seeking avenues to grow your savings beyond traditional fixed deposits, aiming for returns that outpace inflation and build substantial capital over time. This is where the power of equity-oriented mutual funds truly shines. These funds invest in stocks of companies, offering the potential for significant capital appreciation.
The key to successful long-term investing lies in patience, discipline, and choosing the right instruments. While the market can seem complex, understanding a few fundamental principles can demystify the process. We’ll explore fund categories that have historically delivered strong performance and provide actionable insights to help you make informed decisions. Remember, the goal isn’t just to invest, but to invest wisely for a secure financial future. Your journey towards significant wealth in 2026 starts with a well-thought-out strategy.
The Power of Equity: Large-Cap and Flexi-Cap Stars
For investors with a long-term horizon, typically five years or more, large-cap equity mutual funds are often a cornerstone of a diversified portfolio. These funds invest predominantly in the top 100 companies by market capitalisation in India. Think of blue-chip stocks – established, stable companies with a proven history of earnings and market dominance. They generally offer more stability than mid-cap or small-cap funds, making them ideal for wealth preservation while still aiming for growth. The Securities and Exchange Board of India (SEBI) has clear guidelines on how these funds are categorized, ensuring a standardized approach to investment.
Complementing large-caps, flexi-cap funds offer unparalleled flexibility. Fund managers in this category can dynamically shift their investments across large, mid, and small-cap stocks based on market conditions and their assessment of opportunities. This adaptability allows them to tap into pockets of growth wherever they may arise, potentially leading to superior returns. The ability to pivot quickly between market segments makes them a powerful tool for navigating different economic cycles. We’ve seen consistently strong performance from leading flexi-cap funds over the past decade, demonstrating their efficacy in wealth creation.
Balanced Advantage Funds: A Prudent Mix for Stability
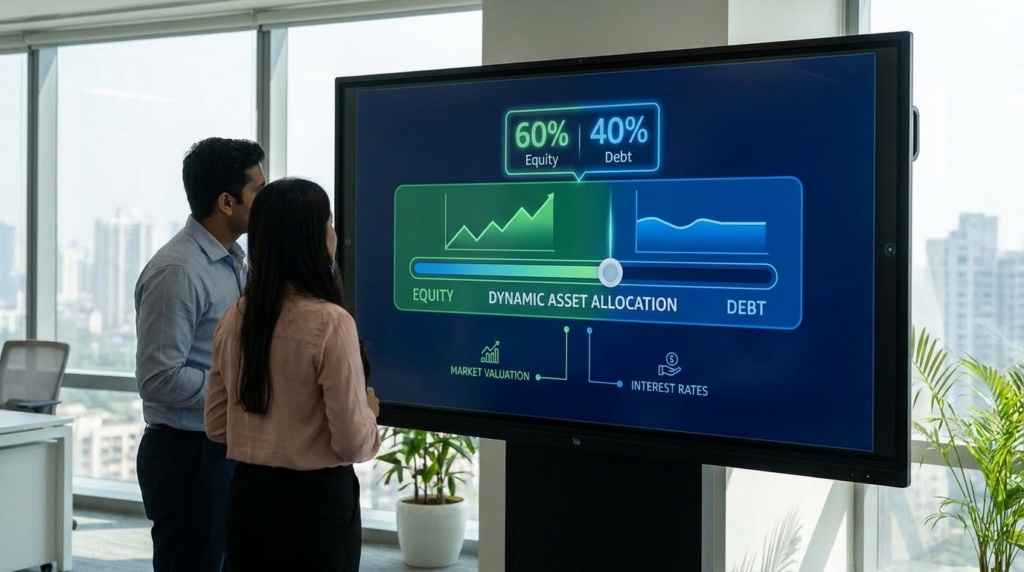
In times of market uncertainty, which are inevitable even in a growth-oriented economy, Balanced Advantage Funds (BAFs), also known as dynamic asset allocation funds, offer a compelling proposition. These funds aim to provide a balance between equity and debt instruments, dynamically adjusting their allocation based on market valuations. When equity markets are perceived as overvalued, they tend to reduce equity exposure and increase debt, thereby cushioning potential downsides. Conversely, when markets are undervalued, they increase equity allocation to capture potential upside.
This strategic allocation aims to mitigate risk while still participating in equity market gains. For investors who prefer a less hands-on approach or are slightly more risk-averse but still want to beat inflation significantly, BAFs can be an excellent choice. They provide a smoother ride compared to pure equity funds, making them suitable for those nearing retirement or with a moderate risk tolerance. The inherent diversification within a single BAF reduces the need for investors to manage multiple funds across different asset classes.
The Case for Sectoral and Thematic Funds (with Caution)
While broad-market funds like large-cap and flexi-cap are generally recommended for beginners, sectoral and thematic funds can play a role in a well-diversified long-term portfolio, provided you understand their inherent risks. Sectoral funds focus on a specific industry, such as IT, pharmaceuticals, or banking. Thematic funds, on the other hand, invest in companies that are part of a particular theme, like infrastructure, consumption, or ESG (Environmental, Social, and Governance) investing.
These funds have the potential for very high returns if the chosen sector or theme performs exceptionally well. For instance, a well-timed investment in an IT sector fund during a digital transformation boom could yield spectacular results. However, their concentrated nature means they are also susceptible to significant downturns if the sector faces headwinds. For example, a downturn in global semiconductor prices could severely impact an electronics manufacturing fund. It’s crucial to research thoroughly and invest only a small portion of your portfolio in these specialized funds. A surprising fact is that the Indian mutual fund industry has seen a significant rise in ESG-themed funds, reflecting global trends and growing investor awareness. You can find more information on SEBI’s categorisation of these funds on their official website.
Key Metrics to Evaluate Your Fund Choices
Selecting the right mutual fund requires looking beyond just past returns. Several key metrics can help you evaluate a fund’s potential for long-term success. Firstly, Consistency of Performance is paramount. A fund that has consistently performed well across different market cycles, rather than having one or two spectacular years followed by poor ones, is generally a safer bet. Look at rolling returns over 3, 5, and 10 years. Secondly, the Fund Manager’s Experience and Track Record are crucial. An experienced manager with a stable philosophy often navigates market volatility more effectively.
Thirdly, Expense Ratio matters. This is the annual fee charged by the fund house to manage your money. A lower expense ratio means more of your returns stay with you. While a slightly higher expense ratio might be justifiable for a fund with exceptional performance, generally, you want to keep this as low as possible. Fourth, Risk Ratios like the Sharpe Ratio and Sortino Ratio can indicate how much risk the fund took to generate its returns. A higher Sharpe Ratio suggests better risk-adjusted returns. The Association of Mutual Funds in India (AMFI) provides a glossary of terms that can help you understand these metrics.
“Long-term investing in mutual funds isn’t about timing the market; it’s about time *in* the market, powered by patience and informed choices.”
Building Your Long-Term Mutual Fund Portfolio for 2026
As you build your portfolio for 2026, remember that diversification is your best friend. Don’t concentrate all your investments in a single fund or even a single category. A balanced portfolio might include a core holding in a large-cap or flexi-cap fund, a portion in a BAF for stability, and perhaps a small allocation to a promising sectoral or thematic fund if you have done your due diligence. The goal is to spread your risk across different asset classes, sectors, and fund management styles.
Consider the power of Systematic Investment Plans (SIPs). SIPs allow you to invest a fixed amount at regular intervals, averaging your purchase cost over time and instilling discipline. This is particularly beneficial in volatile markets, as you buy more units when prices are low and fewer when prices are high. For 2026, aim for a portfolio that aligns with your individual risk tolerance, financial goals, and investment horizon. Regularly reviewing and rebalancing your portfolio annually will ensure it stays aligned with your objectives and market dynamics. A surprising insight for many is that starting an SIP with as little as ₹500 per month can lead to significant wealth creation over 15-20 years, thanks to the power of compounding. You can explore various SIP options and calculators on the Mutual Funds Sahi Hai website, an initiative by AMFI.
Frequently Asked Questions
What is the minimum investment horizon for long-term mutual funds?
For equity-oriented mutual funds, a minimum investment horizon of at least 5 years is generally recommended. This allows sufficient time for the investments to grow and to ride out short-term market fluctuations.
How often should I review my mutual fund investments?
While you should avoid checking your portfolio daily, it is advisable to review your mutual fund investments at least once a year. This allows you to assess performance, rebalance your portfolio if necessary, and ensure it remains aligned with your financial goals.
Are there any tax implications for long-term mutual fund investments?
Yes, there are tax implications. For equity-oriented funds held for over one year, long-term capital gains (LTCG) are taxed at 10% on gains exceeding ₹1 lakh in a financial year. For debt funds, gains are taxed at your income tax slab rate if held for less than three years, and at 20% with indexation if held for more than three years. It’s wise to consult a tax advisor for personalized guidance.
What is the difference between an ELSS fund and other equity funds?
ELSS (Equity Linked Savings Scheme) funds are equity-oriented mutual funds that offer tax benefits under Section 80C of the Income Tax Act. They have a mandatory lock-in period of three years, which is longer than some other equity funds, but they aim to provide capital appreciation while saving taxes.