Key Takeaways
- UPI 3.0 is poised to revolutionise Indian digital payments with new features like offline transactions, credit facilities, and enhanced security by late 2026.
- Beyond UPI, emerging technologies like AI-powered fraud detection, decentralised finance (DeFi) integrations, and blockchain are set to redefine the fintech landscape in India.
- Consumers and businesses can expect more personalised financial services, seamless cross-border payments, and greater financial inclusion as these innovations mature.
- Navigating this evolving ecosystem will require a proactive approach to understanding new security protocols and embracing digital literacy for maximum benefit.
UPI 3.0: The Next Leap in Digital Payments
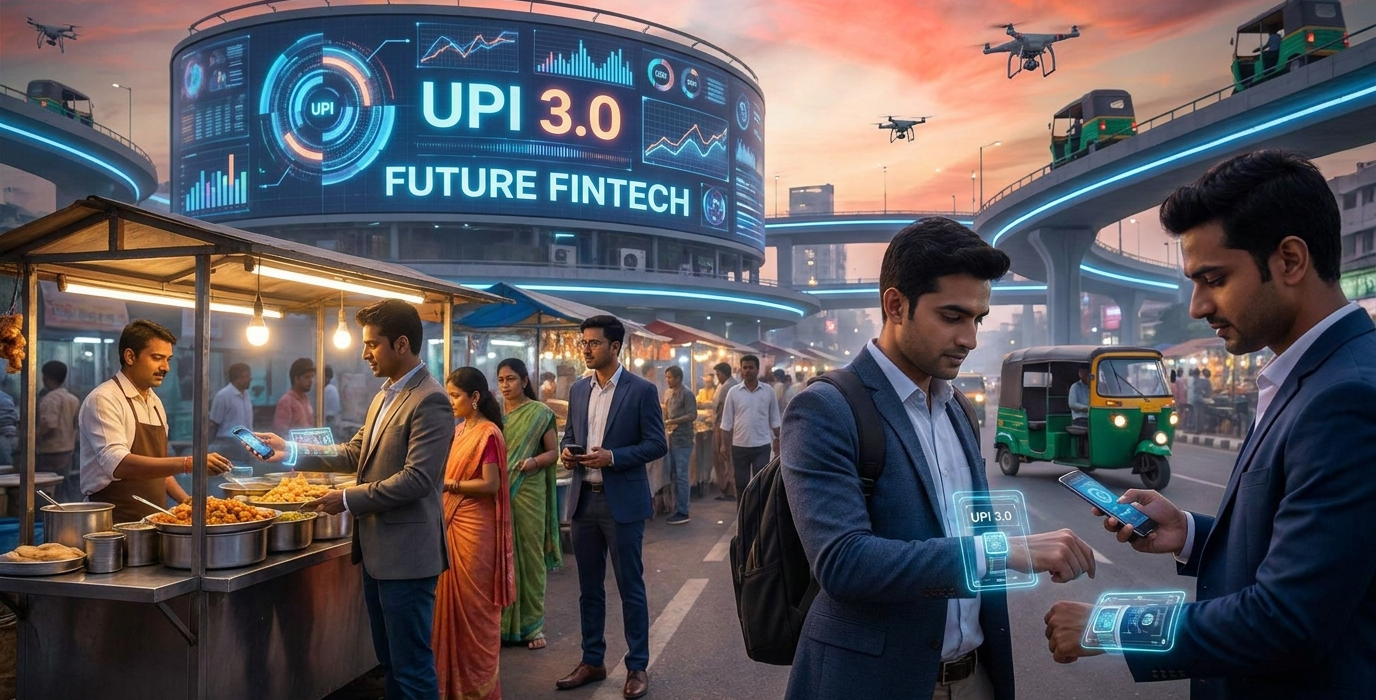
The Unified Payments Interface (UPI) has already transformed India’s digital payment narrative, becoming a globally recognised benchmark for instant, low-cost transactions. As we move through 2026, the next evolutionary stage, UPI 3.0, is no longer a distant dream but a tangible reality on the horizon. This upgrade promises to address current limitations and introduce functionalities that will further democratise digital finance.
Imagine a scenario where you can make a UPI payment even when your mobile network is down. This is one of the most anticipated features of UPI 3.0: robust offline transaction capabilities. Leveraging technologies like NFC (Near Field Communication) and QR codes that can facilitate peer-to-peer transfers without an active internet connection, this will be a game-changer, especially in remote areas where connectivity can be intermittent.
Furthermore, UPI 3.0 is set to introduce credit on UPI. This integration will allow users to link their pre-approved credit lines directly to their UPI accounts, enabling instant credit transactions. This could significantly boost small businesses and individuals seeking quick, short-term financing. The National Payments Corporation of India (NPCI) has been working diligently on the frameworks to ensure this is implemented securely and responsibly.
Security is paramount, and UPI 3.0 will bring enhanced security layers. Expect more sophisticated biometric authentication methods, dynamic security codes, and AI-driven anomaly detection to proactively safeguard against fraudulent activities. The focus is on making the payment process not just convenient but also exceptionally secure, building even greater trust among users.
Beyond UPI: The Rise of AI and Personalisation
While UPI 3.0 captures headlines, the broader Indian fintech ecosystem is buzzing with innovations that extend far beyond immediate payment mechanisms. Artificial Intelligence (AI) is rapidly becoming the backbone of sophisticated financial services, moving from simple chatbots to complex analytical engines. By 2026, AI’s influence will be deeply embedded in how we manage, protect, and grow our money.
One of the most impactful applications of AI is in fraud detection and prevention. Machine learning algorithms can now analyse vast amounts of transaction data in real-time, identifying patterns and anomalies that human oversight might miss. This means a significantly reduced risk of financial fraud for both consumers and businesses. Banks and payment platforms are heavily investing in these AI-powered security systems, making your digital transactions safer than ever.
AI is also driving hyper-personalisation in financial products and services. Forget generic loan offers or investment advice. AI can now assess your individual spending habits, financial goals, and risk appetite to suggest tailored savings plans, investment portfolios, and even insurance policies. Imagine your banking app proactively suggesting you invest a small surplus from your salary into a low-risk mutual fund based on your spending patterns – this is the future we are moving towards.
This personalised approach extends to customer service as well. AI-powered virtual assistants will offer more nuanced and efficient support, understanding complex queries and providing instant, accurate solutions. The goal is to make financial management feel less like a chore and more like a guided, intuitive experience. This shift is crucial for driving greater financial literacy and participation across all demographics.
Decentralised Finance (DeFi) and Blockchain’s Growing Footprint
The buzz around Decentralised Finance (DeFi) and blockchain technology, once confined to cryptocurrency enthusiasts, is now entering the mainstream fintech conversation in India. While widespread adoption is still evolving, 2026 marks a pivotal year where these technologies are poised to offer tangible benefits and reshape fundamental aspects of financial services.
Blockchain, the distributed ledger technology underpinning cryptocurrencies, offers unparalleled transparency and security. In the fintech context, this translates to more secure record-keeping, faster settlement times for cross-border transactions, and the potential for creating immutable digital identities. Imagine a digital KYC (Know Your Customer) process that is instantly verifiable and tamper-proof across multiple institutions, eliminating repetitive paperwork and lengthy verification times.
DeFi, on the other hand, aims to recreate traditional financial systems without intermediaries like banks. Think of peer-to-peer lending platforms built on smart contracts, where interest rates are determined by algorithms rather than a central authority. This could offer more competitive rates for both borrowers and lenders, opening up new avenues for capital generation, particularly for small and medium enterprises (SMEs) in India.
While regulatory frameworks are still catching up, we are seeing pilot projects and early integrations. For instance, using blockchain for supply chain finance can provide greater visibility and trust between buyers, sellers, and financiers. The potential for tokenisation of assets, allowing fractional ownership of real estate or even art, is another exciting frontier that blockchain and DeFi could unlock, making investment opportunities more accessible to a wider audience.
“The convergence of UPI’s ubiquity with the security and transparency of blockchain, and the personalisation offered by AI, is creating a financial ecosystem in India that is not just advanced, but truly inclusive.”
The Future of Cross-Border Payments and Remittances
For millions of Indians working abroad and their families back home, remittances are a lifeline. The current systems, while functional, can be slow and expensive. The fintech innovations on the horizon in 2026 promise to make cross-border payments faster, cheaper, and more transparent than ever before.
The integration of blockchain technology is a key driver here. By removing intermediaries and streamlining the transfer process, blockchain-based remittance solutions can significantly reduce transaction fees. This means more money reaching the intended recipients, which is crucial for many households relying on these funds for daily expenses, education, and healthcare.
Furthermore, advancements in digital identity and KYC solutions built on secure ledgers will expedite the verification process for international transfers. This will not only speed up transactions but also reduce the chances of errors and fraud, making the entire experience smoother for both the sender and the receiver. Imagine sending money to your family in Kerala from London with the same ease and speed as sending money across town.
Several fintech companies are also exploring stablecoins and central bank digital currencies (CBDCs) as potential mediums for cross-border transactions. While CBDCs are still in their nascent stages globally, their potential to offer a stable, digital alternative to traditional fiat currencies could revolutionise international remittances. The aim is to create a seamless flow of funds, bridging geographical and financial divides effectively.
Financial Inclusion: Reaching the Unbanked and Underbanked
India’s journey towards comprehensive financial inclusion has been significantly propelled by digital innovation. As we look towards 2026, emerging fintech trends are set to deepen this impact, bringing essential financial services to the doorstep of every Indian, regardless of their geographical location or economic standing.
The expansion of offline payment capabilities through UPI 3.0 and other technologies is critical. For the vast segments of the population in rural and semi-urban areas with limited or no internet access, the ability to make digital payments without connectivity is a true game-changer. This empowers small shopkeepers, farmers, and daily wage earners to participate more fully in the digital economy.
Moreover, the use of alternative data for credit scoring is opening up avenues for individuals who lack traditional credit histories. Fintech platforms are leveraging data from mobile phone usage, utility bill payments, and even social media behaviour (with user consent) to assess creditworthiness. This allows for the provision of small-ticket loans and micro-insurance products to previously underserved populations, fostering entrepreneurship and financial resilience.
The government’s push for digital public infrastructure, coupled with private sector innovation, is creating a synergistic environment. Initiatives like the Pradhan Mantri Jan Dhan Yojana (PMJDY) have laid the groundwork, and new fintech solutions are now building upon this foundation to offer a comprehensive suite of services, including savings, credit, insurance, and investment opportunities, tailored to the needs of the last mile.
Navigating the Evolving Fintech Landscape: What You Need to Know
The rapid evolution of the fintech landscape in India, driven by innovations like UPI 3.0, AI, and blockchain, presents immense opportunities but also necessitates a proactive approach from consumers and businesses alike. Staying informed and adapting to these changes will be key to harnessing the full potential of these advancements.
For individuals, this means embracing digital literacy and security best practices. Understanding the new features of UPI 3.0, such as offline transactions and credit linking, is important. Equally crucial is staying vigilant about new security protocols. Always verify transaction details, be wary of unsolicited requests for personal information, and utilise the enhanced security features offered by your banking and payment apps. A surprising fact is that the NPCI is exploring quantum-resistant cryptography for future UPI versions, a testament to their forward-thinking approach to security.
Businesses, particularly SMEs, stand to benefit immensely from the increased efficiency and accessibility of financial services. Leveraging AI-powered tools for financial management, exploring DeFi for alternative funding, and adopting secure digital payment gateways will be crucial for growth. This digital transformation allows businesses to streamline operations, reduce costs, and reach a wider customer base, both domestically and internationally.
The rise of embedded finance, where financial services are integrated seamlessly into non-financial platforms (like e-commerce apps offering instant loans at checkout), is another trend to watch. This convenience will become increasingly commonplace, requiring users to be aware of the financial products they are engaging with. Another fascinating development is the potential for gamified financial learning tools powered by AI, making personal finance education more engaging and accessible for younger generations.
Frequently Asked Questions
What are the main benefits of UPI 3.0 for the average user?
UPI 3.0 will bring offline transaction capabilities, allowing payments even without internet, and credit on UPI, enabling instant credit transactions. It also promises enhanced security features for safer digital payments.
How is AI impacting Indian fintech beyond payment apps?
AI is driving advanced fraud detection, hyper-personalisation of financial products like loans and investments, and providing more efficient customer service through intelligent virtual assistants.
Is blockchain technology safe for everyday financial transactions in India?
Blockchain offers enhanced security and transparency. While still evolving, its integration in areas like cross-border payments and digital identity is enhancing safety and efficiency, with ongoing development to ensure robust security measures.
Will these new fintech innovations make financial services more accessible to rural populations?
Yes, features like offline UPI transactions, alternative data credit scoring, and simplified digital onboarding are specifically designed to improve financial inclusion for unbanked and underbanked populations, including those in rural areas.
What should I do to prepare for these changes in Indian fintech?
Focus on digital literacy, understand the new features and security protocols, and stay informed about evolving financial products. For businesses, consider adopting new technologies to improve efficiency and customer outreach.